You pay for home insurance every month or year, so it’s easy to assume that if something goes wrong at home, your insurer will take care of it.
Unfortunately, home insurance doesn’t work quite like that.
Buildings and contents policies can provide valuable protection against events such as fires, storms, theft and certain types of water damage. But they don’t cover every problem that can happen to a property.
Some claims can be rejected because the damage developed gradually. Others may fall under maintenance exclusions, exceed limits for valuable belongings or involve circumstances that require additional cover.
And with colder weather approaching, understanding the difference between insured damage and routine home maintenance becomes particularly important.
Here are seven areas where homeowners and renters can easily assume they’re protected when the reality may be more complicated.
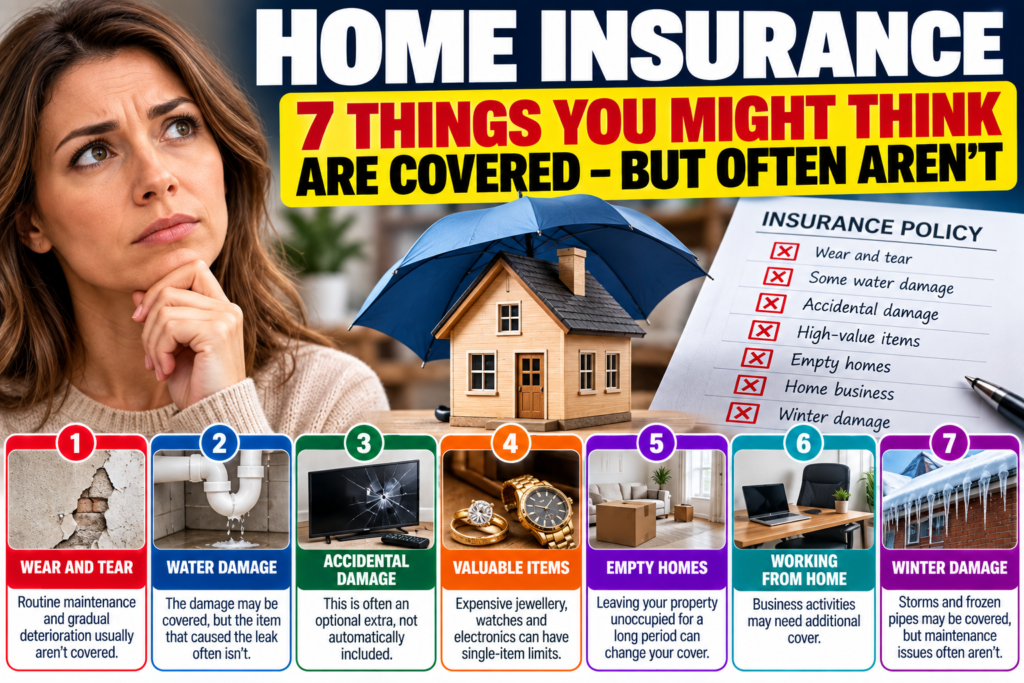
1. Wear and Tear Isn’t Usually an Insured Event
This is one of the biggest misunderstandings about home insurance.
Insurance is primarily designed to protect against unexpected events, not to pay for everything in your home that eventually wears out.
Imagine your roof has been deteriorating for years.
One day you notice water entering the loft.
You might reasonably think:
“I have buildings insurance, so the roof should be covered.”
But if an insurer concludes that the roof failed mainly because of age, deterioration or poor maintenance, the repair itself may not be covered.
The same principle can apply to problems involving:
- ageing sealant,
- worn flooring,
- deteriorating pipes,
- old appliances,
- damaged pointing,
- rotten window frames,
- or neglected gutters.
This doesn’t mean insurers automatically reject every claim involving an older home.
The cause of the damage matters.
For example, sudden storm damage is different from a roof that has gradually deteriorated for many years.
A useful way to think about insurance is:
Insurance helps protect against unexpected insured events. Maintenance remains the homeowner’s responsibility.
That distinction can determine whether a claim succeeds.
2. A Water Leak Doesn’t Mean Everything Is Automatically Covered
Escape-of-water claims can be among the most expensive household insurance problems.
A pipe bursts upstairs and water damages the ceiling below.
A washing-machine connection fails.
A hidden leak slowly damages flooring.
Many policies provide some form of protection for sudden water damage, but there can be an important difference between the damage caused by the water and the item that caused the leak.
Suppose an old pipe fails.
Your policy might potentially cover insured damage to ceilings, flooring or decorations while not necessarily paying to replace the deteriorated pipe itself.
Finding the source of a hidden leak can also involve another concept called trace and access.
This can cover the cost of locating the source of a leak and accessing it, such as opening a wall or lifting flooring.
But limits and conditions vary between policies.
Slow leaks can be particularly problematic.
If water has been escaping for months and there are obvious signs that weren’t addressed, an insurer may investigate whether reasonable steps were taken to prevent further damage.
The practical lesson is simple:
Don’t ignore damp patches, unexplained water marks or changes in water pressure.
Small warning signs can become expensive problems.
Read:Energy Price Cap October 2026: What the 4% Rise Actually Means for Your Bill
3. Accidental Damage May Be an Optional Extra
Imagine dropping your television while moving furniture.
Or knocking a tin of paint across an expensive carpet.
Or accidentally damaging a kitchen worktop.
Many people assume their standard contents or buildings insurance will automatically pay.
It might not.
Accidental damage cover is often an additional feature rather than something included at the same level in every basic policy.
Exactly what qualifies also varies.
A policy might cover accidental damage to televisions but have different rules for mobile phones, laptops or items taken outside the home.
Buildings accidental damage and contents accidental damage can also be treated separately.
That’s why the phrase “I have home insurance” doesn’t tell you enough.
You need to know what type of cover you’ve actually purchased.
Before buying accidental-damage cover, read its exclusions as well.
Insurance doesn’t normally protect against deliberate damage by the policyholder, and exclusions can apply to damage caused by pets, building work or particular types of possessions.
4. Expensive Jewellery and Electronics Can Have Limits
Contents insurance might provide £50,000 of total cover.
That doesn’t necessarily mean your £8,000 watch is automatically insured for its full value.
Policies can impose a single-item limit.
For example, an insurer might limit how much it will pay for one unspecified valuable item.
Items worth more than that threshold may need to be individually declared.
This can matter for:
- engagement rings,
- jewellery,
- watches,
- artwork,
- musical instruments,
- collectibles,
- cameras,
- and expensive technology.
Another important question is where the item is covered.
Your contents insurance may protect a laptop while it’s inside your home but not necessarily when you take it to a café or on holiday.
For that, you may need personal possessions cover away from home.
Don’t wait until something is stolen to discover the difference.
Make a list of your most valuable possessions and check whether any exceed your policy’s single-item limit.
For particularly valuable items, keeping receipts, photographs, serial numbers and valuations can also make a future claim easier to support.
5. Leaving Your Home Empty Can Change Your Cover
Going away for a weekend isn’t normally the issue.
Leaving a property unoccupied for a long period can be.
Many home insurance policies contain conditions relating to unoccupancy.
The exact number of days varies by insurer and policy, so you should check your own wording rather than assuming a universal limit.
Why do insurers care?
An empty home presents different risks.
If a pipe bursts while you’re living there, you may discover it within minutes.
If you’re away for several weeks, water could continue flowing unnoticed.
An empty property can also face increased risks involving theft, vandalism and undetected maintenance problems.
This can become relevant if you’re:
- taking a long trip,
- moving home before selling the old property,
- renovating,
- staying elsewhere temporarily,
- or dealing with a property after someone has died.
If you know your home will be empty for an extended period, contact your insurer beforehand.
You may need additional cover or have to meet conditions such as heating the property, turning off water or arranging regular inspections.
6. Working From Home Can Affect What Needs Insuring
Millions of people now work from home at least some of the time.
Answering emails from a company laptop is very different from running a business that stores stock, receives customers or uses specialist equipment at home.
Standard home insurance may cover ordinary home-office arrangements, but business activities can introduce additional risks.
Ask yourself:
can customers visit my property?
Do I keep business stock at home?
I use expensive specialist equipment?
Do I employ anyone who works from the property?
Have I made structural changes for the business?
If the answer to any of these is yes, tell your insurer.
Don’t assume that because an activity takes place inside your home, standard domestic insurance automatically covers it.
There is also a distinction between equipment you own and equipment supplied by an employer.
A company laptop, for example, may already be insured by your employer.
If you’re self-employed, you may need separate business insurance depending on what you do.
The safest approach is transparency.
Tell the insurer how the property is actually being used.
7. Winter Damage Isn’t Automatically Covered Just Because It’s Winter
Cold weather can create serious household problems.
Frozen pipes can burst.
Storms can damage roofs.
Heavy rain can cause water ingress.
Trees and fences can fall.
But the existence of bad weather doesn’t automatically guarantee that every resulting repair will be paid for.
Insurers may consider whether the damage resulted from an insured event and whether the property had been reasonably maintained.
Consider a roof.
If a severe storm damages a roof that was previously in good condition, that’s very different from discovering that a neglected roof had already been leaking for months.
Frozen pipes provide another example.
If you’re away during cold weather, your policy may contain conditions about heating the property or draining the water system.
Failing to follow policy conditions can complicate a claim.
Gutters are worth attention too.
Blocked gutters can cause overflowing water to penetrate parts of a property.
Cleaning them isn’t particularly exciting, but insurance isn’t intended to replace ordinary preventative maintenance.
As winter approaches, basic checks can reduce the chance of both property damage and insurance disputes.
How to Check Your Home Insurance Properly
You don’t need to memorise a 70-page policy document.
But there are several sections worth checking.
Start with your policy schedule.
This usually summarises what you’ve purchased, the insured address, coverage amounts and optional extras.
Then check your policy wording for exclusions and conditions.
Pay particular attention to:
Buildings cover — protection relating to the structure of your home.
Contents cover — belongings inside the property.
Accidental damage — whether it’s included and what it covers.
Personal possessions — whether valuables are protected away from home.
Single-item limits — the maximum for individual valuables unless separately specified.
Excess — the amount you may have to contribute toward a claim.
Unoccupancy conditions — what happens if the property is left empty.
Trace and access — what protection exists when locating hidden water leaks.
Also check that the value of your contents is realistic.
People frequently underestimate how much replacing everything would cost.
Imagine replacing your:
beds,
sofas,
televisions,
computers,
clothing,
kitchen equipment,
furniture,
jewellery,
and other belongings
all at once.
The total can be much higher than expected.
Buildings insurance requires a different calculation.
The amount needed to rebuild a home isn’t necessarily the same as its market value.
A £500,000 property’s rebuild cost could be considerably different from its selling price because the land itself isn’t being rebuilt.
Finally, tell your insurer when important circumstances change.
Examples can include major renovations, changes in occupancy, running a business from home or purchasing unusually valuable items.
Insurance works best when the insurer has accurate information about the risk it’s covering.
Read:What Is Inflation and Why Does Your Money Buy Less Over Time?
The Bottom Line
Home insurance can provide extremely valuable protection, but it isn’t a maintenance contract or a guarantee that every household problem will be paid for.
The biggest mistake is assuming:
“Something went wrong in my house, therefore insurance covers it.”
Instead, the important questions are:
What caused the damage?
Is that cause insured?
Are there exclusions or limits?
Did I comply with the policy conditions?
Before winter arrives, spend ten minutes reviewing your policy.
Check your accidental-damage cover.
Look at valuable-item limits.
Find the unoccupancy rules.
Check whether belongings are covered away from home.
And deal with obvious maintenance issues before they become expensive.
The best time to discover what your home insurance doesn’t cover is before you need to make a claim.
Frequently Asked Questions
Does home insurance cover wear and tear?
Usually not. Home insurance is generally designed for specified unexpected events rather than gradual deterioration and routine maintenance.
Does home insurance cover a leaking roof?
It depends on the cause. Sudden insured damage may be covered, while deterioration caused by age or poor maintenance may not be.
Is accidental damage automatically included?
Not always. Some policies include certain accidental-damage protection, while others offer broader accidental damage as an optional extra.
Are expensive watches and jewellery covered?
They may be, but policies often have single-item limits. High-value possessions may need to be declared individually.
Does home insurance cover my belongings outside the house?
Not necessarily. You may need personal-possessions or away-from-home cover.
Can I leave my house empty while travelling?
Yes, but extended periods of unoccupancy can affect insurance. Check your policy’s specific time limits and conditions.
Leave a Comment